Canadian mortgage calculator — term and amortization
A Canadian mortgage term is the period covered by the current agreement; amortization is the longer repayment horizon. This fixed-rate tool compares monthly, semi-monthly, biweekly, weekly and accelerated payment plans, and shows the balance remaining at the end of your selected term. All six frequencies were exercised in the FCAC calculator before implementation.
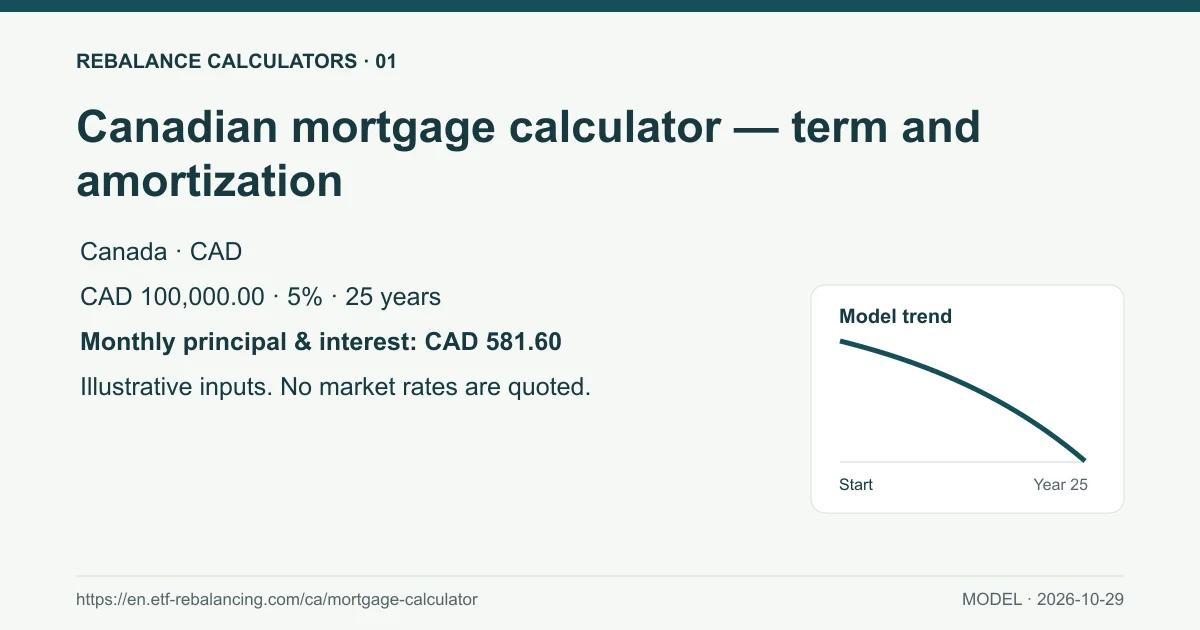
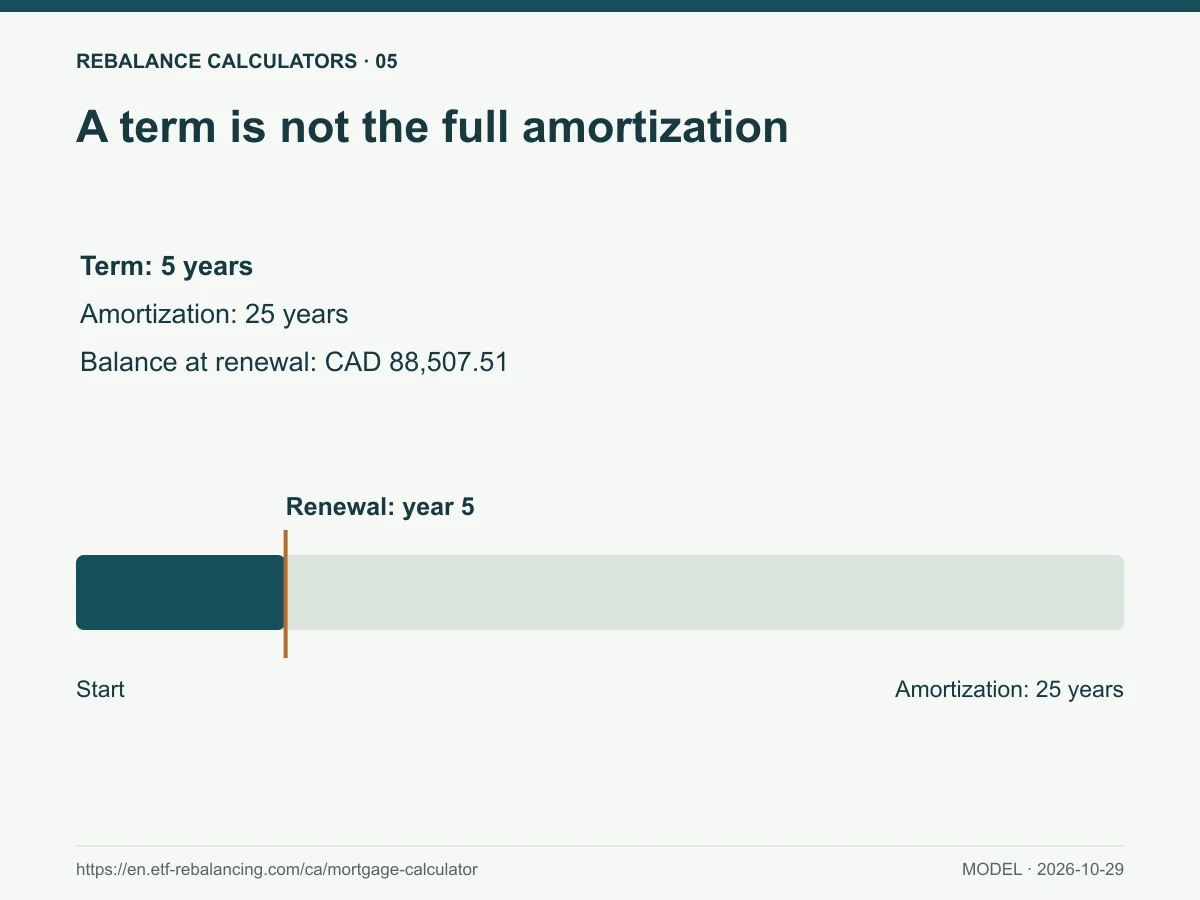
For example, CAD 100,000.00 at 5% over 25 years produces an estimated CAD 581.60 monthly principal-and-interest payment. After the 5-year term, the estimated balance is CAD 88,507.51.
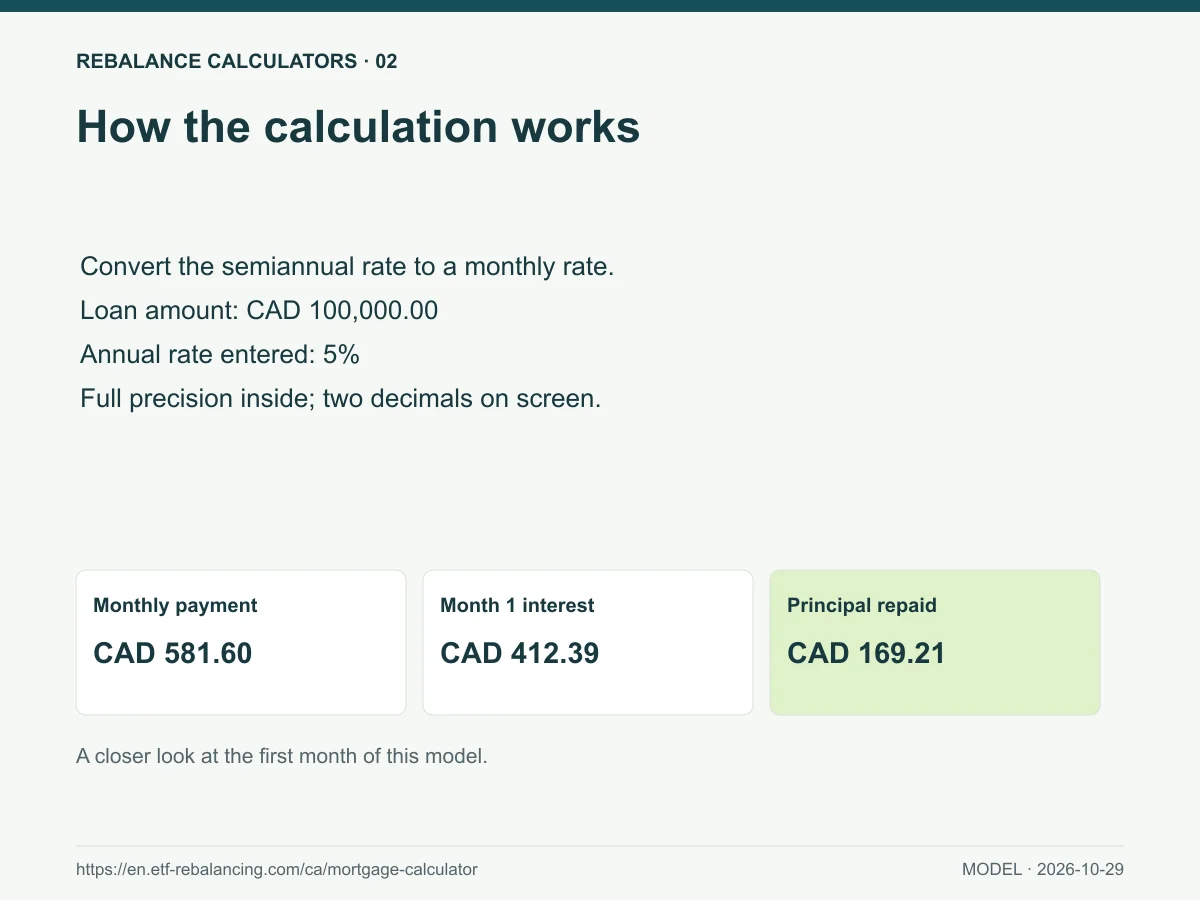
How the calculation works
Convert the quoted annual rate j to a monthly rate: r = (1 + j ÷ 2)^(1 ÷ 6) − 1, using j as a decimal. For the reviewed regular nonmonthly model, prorate that equivalent monthly rate as r × 12 ÷ payments per year and apply the level-payment formula. Accelerated biweekly pays half the monthly payment 26 times a year; accelerated weekly pays one quarter 52 times. Accelerated interest uses the equivalent period rate (1 + j ÷ 2)^(2 ÷ payments per year) − 1. This independently implemented FCAC-style model does not represent every lender’s contract. The amortization determines the payment; the term determines the renewal-balance checkpoint.
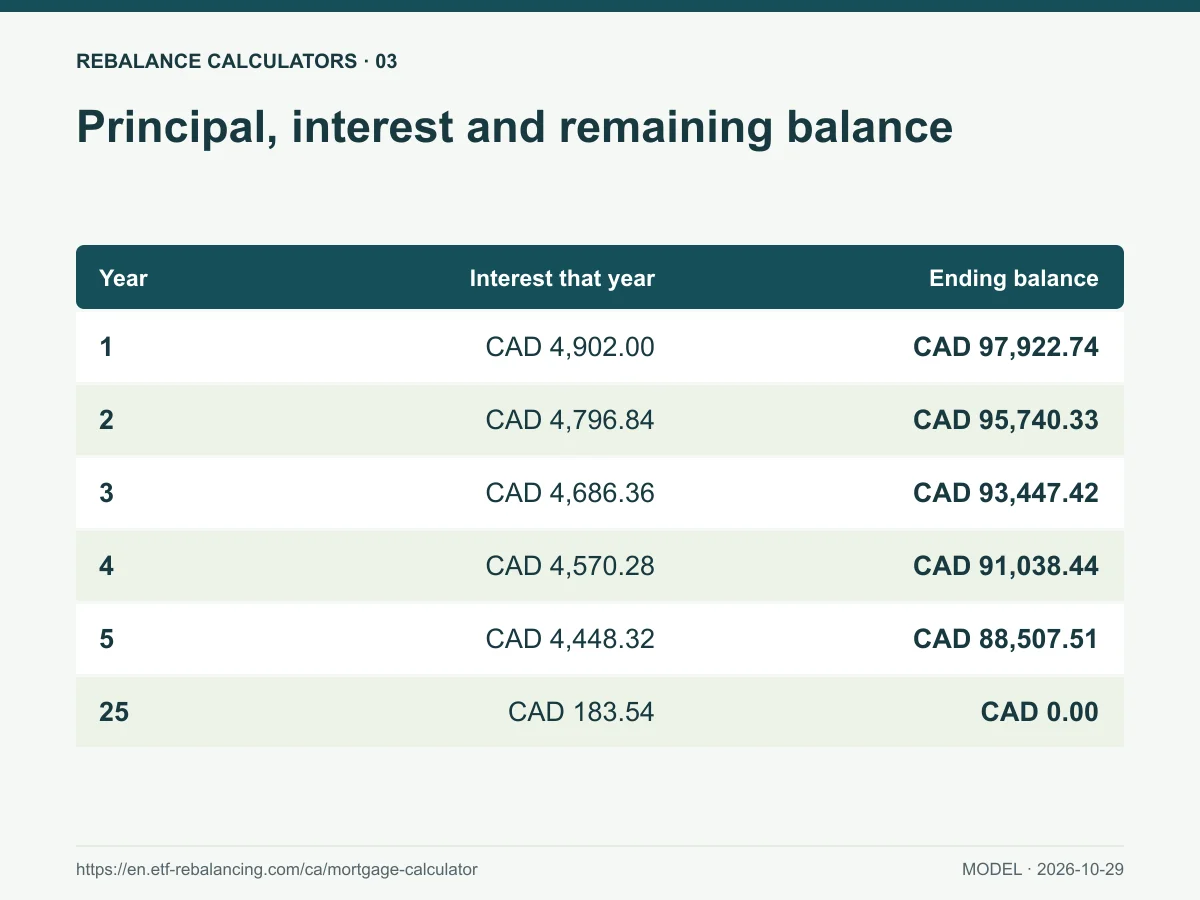
An example, year by year
These are model outputs for the example above. They are not lender offers or a forecast of actual returns. Interest is shown for each individual year; ending balance is the balance at that year’s end.
| Year | Principal paid | Interest | Ending balance |
|---|---|---|---|
| 1 | CAD 2,077.26 | CAD 4,902.00 | CAD 97,922.74 |
| 2 | CAD 2,182.42 | CAD 4,796.84 | CAD 95,740.33 |
| 5 | CAD 2,530.94 | CAD 4,448.32 | CAD 88,507.51 |
| 25 | CAD 6,795.72 | CAD 183.54 | CAD 0.00 |
From your values to a saved result
- Enter your own amounts and rate. Check the currency and duration before continuing.
- Choose View results to open your separate result page. You can return to change any value.
- Read the headline number alongside the assumptions and yearly table. Save every payment or compounding period in Excel or a yearly summary in PDF.
What the headline number means
The balance at term end is the amount that would remain when your current term expires. It is not an additional fee, and a future renewal rate is not built into that number. The full-amortization schedule assumes your current rate continues.
Check these assumptions
- This fixed-rate FCAC-style model uses the reviewed rate convention for the selected payment frequency; lender conventions may differ.
- The term cannot exceed the amortization period. The remaining balance is shown at the end of that term.
- Full-amortization figures assume the same rate continues after renewal; future renewal rates are unknown.
- Prepayments, mortgage default insurance, property taxes, fees and lender-specific day-count adjustments are excluded.
Common questions
How is the term different from amortization?
A five-year term can sit inside a 25-year amortization. The payment uses the 25-year horizon, while the five-year checkpoint shows what you still owe when the current agreement ends.
Why does the payment differ from the US calculator?
The compounding convention is different. This Canadian fixed-rate model converts a semiannually compounded annual rate into its equivalent monthly rate; the US model divides a nominal annual rate by 12.
Can I calculate accelerated biweekly payments?
Yes. Choose Accelerated biweekly or Accelerated weekly. The results compare all six frequencies with the same loan and rate. Accelerated plans pay the equivalent of 13 monthly payments per year. This version does not model separate lump-sum or recurring prepayments; use your lender’s contract or the FCAC tool for those scenarios.
Will the payment remain the same after renewal?
Not necessarily. The full-amortization projection holds the rate constant for comparison. A renewal at a different rate changes future payments and interest.
Does this cover every Canadian mortgage?
No. It is a defined fixed-rate scenario. Variable-rate products, different compounding agreements, fees or insurance can produce different results.
Has the example been checked against an official tool?
Yes. For CAD 100,000 at 5%, with 25-year amortization and a five-year term, this model and FCAC both display a CAD 581.60 monthly payment. Our full-precision term balance rounds to CAD 88,507.51; FCAC displays CAD 88,507.50. All six frequency payments and term balances were also compared. Accelerated biweekly full-period interest is CAD 62,394.32 here versus FCAC’s CAD 62,394.64; final-payment rounding differs. These are estimates, not a reproduction of the official tool’s internal rounding. Checked October 29, 2026.
Sources and benchmark checks
References checked October 29, 2026. Our calculator implements the stated model independently; it is not an official government tool.